Hidden Angles – Cameco (CCJ)
Uranium producer Cameco (CCJ) has seen a total of 9 Hidden Angles dating back to March 10th. To see every Hidden Angle entry across all symbols, you can sign up for Jaguar Options Pro or take a 4-Week Trial (See HERE). Some of the more recent entries for CCJ include:
June 29th – Cameco disclosed that major tech companies (hyperscalers) currently have “multiple term sheets” out exploring direct long-term uranium purchases — a meaningful step beyond the PPA-style nuclear deals the Street has focused on. Additionally, recent contract settlements are clearing at $100/lb fixed and $150-160/lb ceilings, materially above the $93-95/lb term price reported by UxC/TradeTech, suggesting published benchmarks are understating true contracting economics.
Why It Matters: If tech buyers begin signing direct uranium offtake and realized contract prices are running 5-10% above reported benchmarks, consensus uranium price decks and Cameco’s forward EBITDA are structurally too low.
August 3rd – Westinghouse’s Operating Plants business booked $5.2B in new orders, implying a 1.2x book-to-bill and a ~3-year backlog ($13.2B) — an accelerating order intake that RBC flags as evidence of a step-change in the core services franchise. Separately, potential Korean reactor licensing payments (from KHNP/KEPCO settlement) are explicitly excluded from estimates and represent unmodeled upside, while AP1000 unit economics quietly improved (project value capture raised to 40-45% from 25-40%, EBITDA margin to 20% from 10-20%).
Why It Matters: A 1.2x replacement ratio on Westinghouse’s steady-state services business plus unpriced Korean royalty optionality suggests the Street is under-modeling the recurring cash-flow engine, not just the AP1000 new-build narrative.
August 6th – The report flags that Orano’s Philippe Coste conversion facility suffered an unplanned three-month weather-related outage in early 2026, cutting full-year output to just 9kt from 13kt in 2025 — a ~31% Y/Y drop at one of the West’s only major conversion facilities. Combined with ConverDyn’s Metropolis being the sole US commercial UF6 plant, this creates an acute Western conversion bottleneck that forces utilities to overfeed enrichment (consuming more U3O8 per SWU), driving latent incremental yellowcake demand that isn’t in consensus supply/demand models.
Why It Matters: A Western conversion supply shock forces enrichment overfeeding, creating a hidden pull on U3O8 demand that could accelerate spot price breakouts and disproportionately benefit CCJ’s uncontracted volumes.
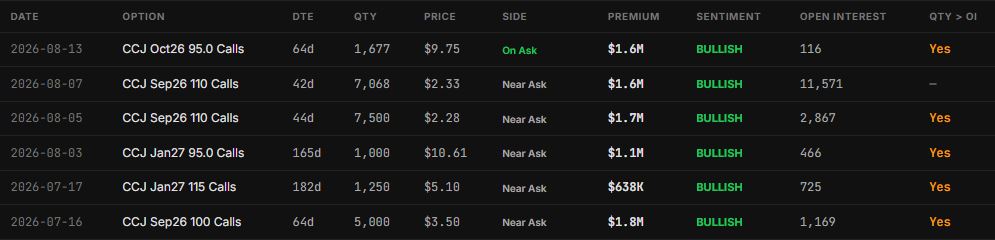
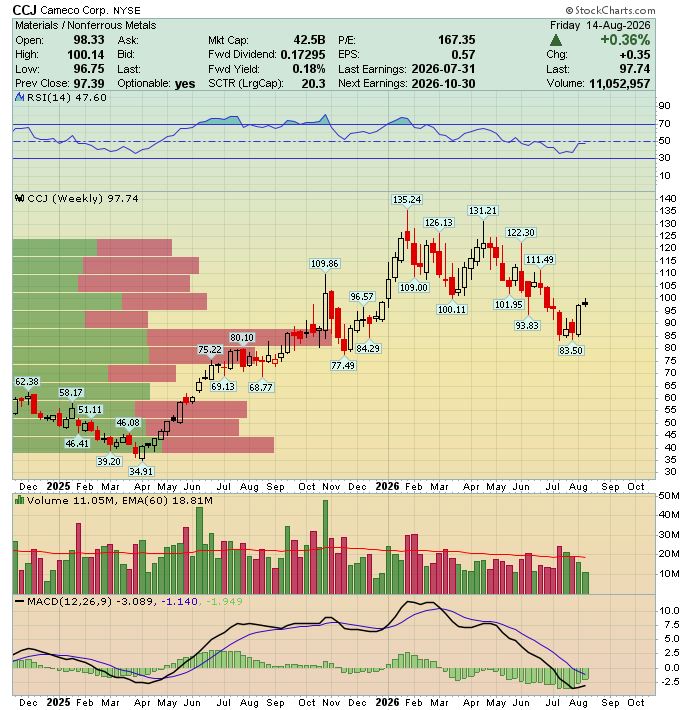
Lastly, I’d be remiss if I didn’t call out some of the recent action we’ve picked up in JaguarFlow. Overall, Cameco has seen total premium of $39M, with $25.7M in bullish flow. The most recent entry took place last Thursday with a buyer of 1,677 October 95 Calls for $9.75 offer, a $1.6M bullish bet. Meanwhile, keep an eye on the September 110 Calls as we’ve seen accumulation on both August 5th and 7th.